
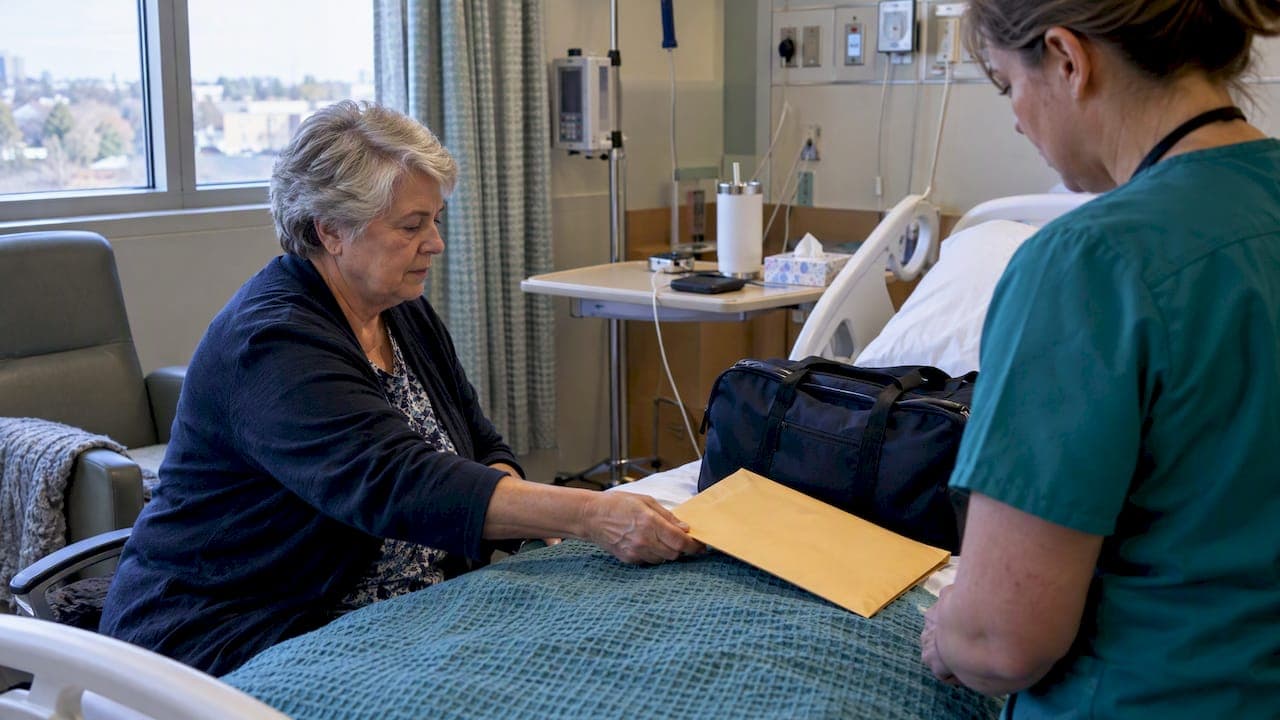
The quickest way to keep your bills paid if you are hospitalized is to combine autopay with a durable financial power of attorney, a trusted contact arrangement at your bank, and a single, easy-to-use document kit for your agent. Start today: set autopay on your top three bills, begin your durable POA paperwork, and add a trusted contact to your bank account. Templates and guidance are available through a clarity session with a solo aging consultant.
TL;DR:
- Setting up autopay for your top three bills and establishing a durable power of attorney can prevent missed payments during hospitalization.
- A durable POA should be signed, notarized, and include several certified copies kept in secure and accessible locations.
- Combining a trusted contact with a POA provides both quick alerts and authorized action, but only the POA grants permission to pay bills.
- Many lenders and utilities offer short-term deferments if you call proactively before due dates, especially during extended hospital stays.
- Having a comprehensive document kit and a clear plan can ensure your bills are managed smoothly without relying solely on chance or informal arrangements.
Table of Contents
- Your 48 hour action plan
- Durable power of attorney: the legal backbone
- Setting up autopay, bank bill pay, and trusted contacts
- Building the document kit your agent will actually use
- Red flags and safeguards worth setting up now
- Pausing or deferring bills during a hospital stay
- Telling creditors and service providers what is happening
- What happens to your credit, and how to fix it
- Working with a hospital social worker or financial counselor
- Managing bills if you become incapacitated without a POA
- Talking to utility companies and lenders during a longer stay
- What this planning is really protecting
- Getting one on one help with your plan
- Sources
- FAQ
Your 48 hour action plan
You do not need a perfect system by tomorrow morning. You need the first layer of protection in place, and that is doable in a weekend.
- Log into your bank or creditor portals and turn on autopay for your mortgage or rent, utilities, and insurance premiums first. These are the bills that cause real damage if missed.
- Decide between creditor autopay and bank bill pay for each account: use creditor autopay when the amount is fixed, and bank bill pay when the payee does not accept direct autopay or the amount varies.
- Call an attorney or search your state's bar association site for a durable power of attorney form, and name a backup agent in case your first choice cannot serve.
- Add one or two trusted contacts to your bank and brokerage accounts, then gather physical copies of your key documents into one folder.
Pro Tip: Set a recurring phone reminder every six months to review autopay amounts and confirm your trusted contact information is still accurate.
Durable power of attorney: the legal backbone
A financial power of attorney lets someone you name, your agent, manage your money and pay your bills on your behalf. The word "durable" is what matters most here: a durable POA stays in effect even if you become incapacitated, while a standard or "springing" POA may not, according to the Consumer Financial Protection Bureau. Without the durable designation, your bills could sit unpaid while a court sorts out who has authority to act, which is exactly the delay you are trying to avoid.
Getting one done right involves a short list of steps:
- Sign the document in front of the witnesses and notary your state requires, since requirements differ by state.
- Request several notarized certified copies, not just one original, and keep the original somewhere secure but findable.
- Bring a copy to your bank before you ever need it and ask whether they require their own internal form or agent certification page.
- Choose your agent based on judgment and reliability, not just closeness or convenience.
Choosing the right person is a real decision, not paperwork to rush through. AARP's guidance on selecting a legal representative points out that your agent should understand your financial priorities and have no conflicts of interest, which matters even more when you are choosing without a spouse to weigh in.
Pro Tip: Ask your bank directly what their agent certification process looks like well before a crisis, since some institutions want their own paperwork on file in advance.
Setting up autopay, bank bill pay, and trusted contacts
Three tools work together here, and each does a different job.
- Creditor autopay pulls a fixed amount directly from your account on a set date, which works well for mortgages, utilities, and insurance.
- Bank bill pay schedules payments from your bank to any payee, including ones who do not accept autopay, through check or electronic transfer.
- A trusted contact is a person your bank can call if they notice unusual activity or cannot reach you, but this role does not come with account access, as the CFPB explains in its guide to trusted contacts.
- Annual or irregular bills, like property tax or an insurance renewal, need a calendar alert since autopay often cannot catch a once a year charge.
A trusted contact and a durable POA are not interchangeable. The trusted contact is a privacy preserving safety valve: your bank can reach out to that person without handing over your account details. Your agent under a POA is the one who can actually log in, transfer funds, or call a creditor to work out a payment plan. Having both means someone gets notified fast, and someone else is authorized to act.
Building the document kit your agent will actually use
An agent with legal authority but no information cannot move quickly. Give them a kit they can open and use the same day.
- Include the signed durable POA, a list of your accounts with creditor contact information, and confirmation screenshots of your current autopay setups.
- Add recent statements for your major accounts and a short written note on your preferences, like which bills matter most and any spending limits you want respected.
- Store the kit in a labeled envelope at home, and keep a second copy in an encrypted cloud folder or a password manager with emergency access built in.
- Tell your agent where both copies live, and walk them through the folder once so nothing is a surprise later.
The National Institute on Aging recommends keeping a central list of accounts, statements, and contacts specifically so a trusted person can step in during a medical crisis without hunting for information. Our living alone financial safety checklist walks through building this kit in more detail.
Pro Tip: A password manager with emergency access, paired with a one page instruction sheet, is safer than writing down passwords on paper your agent could lose.
Red flags and safeguards worth setting up now
Giving someone authority over your money takes trust, and trust works better with structure around it.
- Watch for warning signs like large unexplained transfers, missing statements, or new accounts you did not open.
- Ask your agent to send you or a second trusted person a simple monthly transaction summary.
- Consider setting informal spending limits for routine expenses, with anything larger requiring a conversation first.
- If something looks wrong, contact your bank's fraud department immediately, and consider reaching out to Adult Protective Services or your state's elder services office.
- An elder law attorney can help if a dispute over your agent's authority needs to be resolved formally.
Pausing or deferring bills during a hospital stay
Sometimes the right move is not automating a payment but pausing it. Many lenders and utility companies offer short term deferment or hardship programs, especially for an unexpected hospitalization. Call before a due date passes, not after, since a proactive call is treated very differently from a late payment that already shows up on your account. Ask specifically for a hardship forbearance or deferment plan, and get the terms in writing or by email so there is a record of what was agreed.
Your agent, acting under your durable POA, can make these calls on your behalf if you are unable to. This is one more reason the POA needs to already be set up and recognized by your bank and major creditors before you need it, not scrambled together during a hospital stay. If you do not yet have an agent in place, you can sometimes request a short pause yourself through a secure online portal or by phone, but longer deferments typically require the account holder to be reachable, which may not be possible during a hospitalization.
Keep a short note of which bills you paused, the new due date, and whether interest continues to accrue during the pause. A deferred bill that quietly restarts at full balance, including skipped payments, can create a second financial surprise right when you are recovering.

Telling creditors and service providers what is happening
A short phone call or secure message to each major creditor can prevent a lot of downstream trouble. You do not need to explain medical details. A simple statement that you are hospitalized and temporarily unable to manage your accounts, along with your agent's name and contact information if one is acting on your behalf, is usually enough.
Start with the accounts that have the shortest grace periods or the steepest late fees: credit cards, utilities, and any loan with a strict payment schedule. Mortgage and insurance companies often have dedicated hardship lines, and starting there first can prevent a missed payment from escalating. If your agent is making these calls, have them reference the durable POA by name and be ready to provide a certified copy if asked, since practices vary by institution and some want documentation before discussing your account.
Keep a simple written log, even a few lines, of who you or your agent spoke with, the date, and what was agreed. This matters if a dispute comes up later about whether a company was notified in time.
What happens to your credit, and how to fix it
A missed payment during a hospital stay can show up on your credit report the same way any missed payment would, typically after a payment is 30 days past due. Hospitalization itself is not a protected category that automatically shields your credit, so the real defense is preventing the missed payment in the first place through autopay, deferment, or an agent acting on your behalf.
If a payment is reported late despite your best efforts, most creditors have a process for requesting a goodwill adjustment once you explain the circumstances and show a history of on time payments otherwise. This is not guaranteed, but it is a reasonable first step, and it costs you nothing to ask. You can also dispute an error directly with the credit bureaus if the reported late payment does not match your records.
The best remedy, though, is prevention. A durable POA and working autopay mean a creditor never has a reason to report anything in the first place, which keeps this whole conversation unnecessary.
Working with a hospital social worker or financial counselor
Hospitals often have social workers or financial counselors on staff, and their job includes more than discharge planning. Many can help you think through immediate practical concerns, including who is managing your bills while you are admitted, especially for a longer stay. Ask to speak with one early in your admission rather than waiting until discharge is being discussed.
A social worker cannot act as your financial agent or make payments for you, but they can help connect you with resources, flag that you may need outside financial assistance, and sometimes help reach a family member, friend, or your named agent if you have not already been in touch. For solo agers without someone nearby to visit in person, this connection can matter more than it would for someone with family in the waiting room.
If you already have your document kit prepared, as described earlier, you can hand a copy to the social worker or ask them to help you reach your named agent with the information they need. This turns a hospital staff member who would otherwise have limited ability to help into someone who can actively move your situation forward.
Managing bills if you become incapacitated without a POA
If you are hospitalized without a durable POA in place, your options narrow quickly. Family members, even close ones, do not automatically gain legal authority to access your accounts or pay your bills just because you are incapacitated. A health care proxy does not help here either, since it covers medical decisions only and is separate from financial authority, according to CFPB guidance on bill paying options.
Without a POA, the realistic paths are limited and slower. A court can appoint a guardian or conservator to manage your finances, but this process takes time and often requires a hearing, exactly the delay a durable POA is designed to prevent. Some banks allow a joint account holder to continue paying bills from a shared account, but this requires having set that up in advance. A trusted contact, as useful as that designation is for alerting your bank to a problem, cannot step in and pay bills on your behalf.

This is the clearest argument for setting up a durable POA before you need it rather than after. Our guide on building a power of attorney plan without nearby family walks through the process for solo agers specifically.
Talking to utility companies and lenders during a longer stay
An extended hospital stay changes the conversation with your creditors. A short call about a two week deferment is different from explaining you may be unable to manage your accounts for two months, and most companies have different programs depending on the expected length.
Ask specifically about hardship programs rather than general customer service, since many utility companies and lenders have formal hardship or medical leave accommodations that are not mentioned unless you ask by name. Some utility companies offer protection from service disconnection during a documented medical emergency, though the specifics and required documentation vary by provider and location, so confirm directly with each company. For loans and mortgages, ask about forbearance options and get clear on whether missed payments are added to the end of the loan or due in a lump sum when the forbearance ends.
If your agent is handling these calls under your durable POA, having your account numbers, the general nature of the hospital stay, and an estimated return date ready will make each call faster. A partner resource on financial planning for healthcare costs in retirement can help you think through how these larger payment gaps fit into your overall budget once you are home and recovering.
What this planning is really protecting
I think about the moment someone packs a hospital bag. You fold a sweater, grab your phone charger, and then you set a labeled envelope on the counter, the one with your POA, your account list, your agent's name. That envelope is not about fear. It is about walking into that hospital room knowing your life keeps running without you for a while, and that someone you trust can pick it up exactly where you left it.
This is not a safety net built out of worry. It is an act of self care, the same as locking your door at night or keeping good shoes for a long walk. Planning like this is what lets you stay independent on your own terms, because you decided who helps and how, instead of leaving it to chance.
If you want a starting point, free checklists walk through the basics, and for personalized assistance, clarity sessions are available to help finish the plan with real guidance instead of guesswork.
— Mike
Getting one on one help with your plan
Setting up autopay and drafting a POA are things you can do alone, but choosing the right agent, deciding what limits to set, and making sure your bank will actually recognize the paperwork often benefits from a second set of eyes. A Solo Aging Clarity Session is a 45 minute Zoom conversation built around exactly this kind of planning.
- The session walks through your specific accounts, your document kit, and who might serve as your agent.
- It is designed for solo agers who want a guided conversation rather than figuring it out from articles alone.
- You leave with a clear next step instead of an open ended to do list.
The session costs $97 as a one time fee, and you can book a time that works for you directly through the site. If you are not ready for that yet, start with our free living alone financial safety checklist instead.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Consumer Financial Protection Bureau: What is a power of attorney (POA)?
- CFPB: Trusted contacts for protecting older adults' finances
- AARP: Choosing a legal representative
- National Institute on Aging: Services to help older adults living at home
FAQ
What is the fastest way to keep bills paid if I am hospitalized?
Set up autopay on your biggest recurring bills and put a durable financial power of attorney in place, since autopay keeps routine payments moving while your agent can step in for anything unusual. Adding a trusted contact at your bank gives one more layer of protection if something looks off.
Does a healthcare proxy let someone pay my bills?
No, a healthcare proxy only covers medical decisions and does not grant any financial authority. You need a separate durable financial power of attorney for someone to legally manage your money and pay your bills, as the CFPB explains.
Can a trusted contact access my bank account?
No, a trusted contact can be notified by your bank in an emergency but cannot log in, transfer money, or pay bills on your behalf. That authority requires a durable power of attorney naming them as your agent.
What happens to my bills if I have no agent and get hospitalized?
Your options narrow to a court appointed guardian or conservator, which takes time, or a joint account holder if you already set one up. This is why setting up a durable POA in advance matters so much for solo agers without nearby family to step in informally.
Will a missed payment during hospitalization hurt my credit?
A missed payment is generally reported the same way regardless of the reason, usually once it is 30 days past due. Prevention through autopay or a deferment arranged ahead of time is more reliable than hoping for a goodwill adjustment afterward.