
A Social Security representative payee is the person or organization SSA appoints to receive and manage someone's Social Security or SSI payments when SSA finds they can't manage their own funds. If this might apply to you or someone you love, the next move is simple: call SSA at 1-800-772-1213 or schedule an appointment at your local office.
Here's what to bring and know before you go:
- Photo ID for both the beneficiary and the person applying to be payee
- The beneficiary's Social Security number
- Form SSA-11 (you can start it before your appointment, but SSA typically finishes it with you)
- A clear sense of why a payee is needed: a diagnosis, an accident, a pattern of confusion about bills, or a straightforward wish to plan ahead
TL;DR:
- A representative payee must be appointed by SSA, not through power of attorney or joint accounts, and the appointment considers the person's actual presence in the beneficiary’s life.
- The application process involves a face-to-face interview, where SSA prioritizes the applicant who has regular contact with the beneficiary and understands their daily needs.
- Recordkeeping, including receipts and separate bank accounts, is essential and protects the payee during SSA reviews; receipts should be kept for at least two years.
- Naming up to three preferred payees in advance helps SSA prioritize trusted individuals if the need arises, but verification of the best interest is still required at appointment.
- Misuse of funds can lead to repayment demands, removal or replacement of the payee, and legal action, emphasizing the importance of honest communication and proper oversight.
Table of Contents
- Who Needs a Representative Payee, and How Does SSA Decide?
- How Do You Apply to Become a Payee?
- What Are a Payee's Core Responsibilities?
- Who Is Legally Barred From Serving as a Payee?
- Can You Name Your Preferred Payee in Advance?
- What Happens if a Payee Misuses Funds?
- How Do You Keep This Arrangement Dignified, Not Just Legal?
- Key Takeaways
- What the Rules Don't Tell You About Being Someone's Payee
- Sources
- FAQ
Who Needs a Representative Payee, and How Does SSA Decide?
SSA starts from the assumption that adults can manage their own money. That presumption only shifts when there's real evidence otherwise, and SSA's Representative Payee Program exists specifically for beneficiaries who can't manage or direct someone else to manage their benefits.
The most common candidates are minors, adults with significant cognitive decline, and people with severe mental illness or intellectual disabilities. SSA weighs several kinds of evidence when making this call:
- Medical records or a physician's statement about mental or physical capacity
- Court orders, such as a guardianship or conservatorship finding
- Statements from family, friends, or caseworkers who see the person regularly
One detail trips up a lot of families: having power of attorney does not make you a representative payee. According to SSA's own FAQ for representative payees, POA, a joint bank account, or being an authorized representative are separate legal arrangements. Only SSA's own appointment carries the authority to manage federal benefit payments.
How Do You Apply to Become a Payee?
Applying is more personal than most government paperwork, mostly because SSA wants to know you, not just your name on a form. Here's the general path, based on SSA's guidance on getting help managing money:
- Call or visit. Start with 1-800-772-1213 or your local SSA office to request a payee appointment.
- Complete Form SSA-11. This is the core application, covering your relationship to the beneficiary and how you'd handle their funds.
- Gather documents. You'll need identity documents for yourself and the beneficiary. Organizations applying as payees also need an Employer Identification Number.
- Attend a face-to-face interview. SSA staff will ask about your relationship to the beneficiary, how often you actually see them, and whether you understand their day-to-day needs. Frequency of contact matters more here than most applicants expect. SSA tends to favor the person who's actually present in someone's life.
- Wait for the decision. Timelines vary by office workload and how quickly you can provide documentation.
Pro Tip: If the situation feels urgent, such as a beneficiary who's about to lose housing or utilities, say so explicitly when you call. SSA offices can sometimes expedite an interview when there's an immediate risk to basic needs.
What Are a Payee's Core Responsibilities?
The job has one central rule: the beneficiary's current needs come first, every month, before anything else. That means food, housing, utilities, clothing, and medical care get paid before savings or discretionary spending.
Payees are expected to:
- Use benefits to cover the beneficiary's immediate needs before setting money aside
- Conserve any leftover funds properly, ideally in an account titled in the beneficiary's name
- Keep receipts and bank statements, and maintain a separate account exclusively for the beneficiary's funds
- Enroll in direct deposit or the Direct Express card, since SSA has phased out most paper checks
Recordkeeping isn't busywork. SSA can request a Representative Payee Report at any time, and a payee who can't produce receipts or bank records has a much harder time defending decisions during a review. According to SSA's organizational payee guide, receipts should be kept for at least two years, and organizational payees carry additional annual reporting duties.
Who Is Legally Barred From Serving as a Payee?
Federal regulations draw firm lines around who can hold this role, and for good reason: the position comes with direct control over someone else's income. Under CFR § 404.2022, SSA generally will not appoint:
- Someone convicted of certain felonies, including specific offenses against the beneficiary
- Anyone previously found to have misused benefits as a payee
- Creditors of the beneficiary, except under narrow circumstances
- People who are themselves receiving benefits through a representative payee
SSA can make case-by-case exceptions when it's clearly in the beneficiary's best interest, so a past issue doesn't always end the conversation. If your history includes something on this list, bring documentation of rehabilitation, references, or evidence explaining the circumstances to your interview.
Can You Name Your Preferred Payee in Advance?
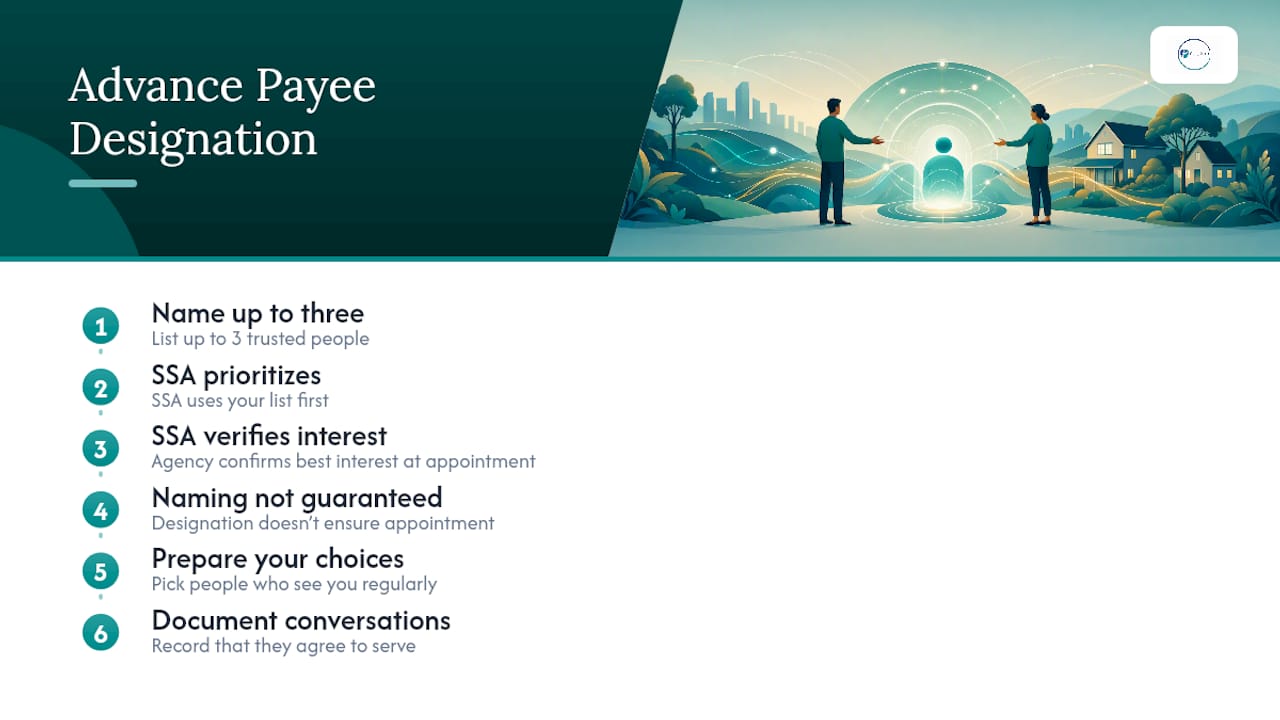
Yes, and this is one of the more useful tools SSA offers solo agers specifically. Through advance designation, you can name up to three people you'd trust to serve as your payee if you ever needed one, and SSA will prioritize those names first, according to SSA's advance designation program.
SSA still verifies best interest at the time of appointment. Naming someone doesn't guarantee the role. If you're building this list, think about who actually sees you regularly and document your conversation with them, since a surprised payee is a shaky one. Resources like Aging Solo's guide to finding a trusted companion can help you think through who belongs on that list.
What Happens if a Payee Misuses Funds?
SSA doesn't just hand over benefits and walk away. Oversight includes periodic Representative Payee Reports, site reviews, and occasional visits from Protection & Advocacy organizations, especially for organizational payees managing many beneficiaries.
If a beneficiary or family member suspects misuse, here's the practical path:
- Document specifics. Note missing payments, unexplained account activity, or bills going unpaid despite benefits arriving.
- Contact SSA directly to report suspected misuse and request a review.
- Provide evidence such as bank statements, receipts, or witness accounts if you have them.
- Request a change of payee or direct payment if the beneficiary can demonstrate improved capability.
If misuse is confirmed, SSA can require repayment, remove the payee immediately, and refer the case for civil or criminal action. Beneficiaries also have the right to appeal a payee decision, and that appeal generally must be filed within 60 days of the notice.
According to SSA's FAQ for beneficiaries with a representative payee, this reporting and review structure exists precisely to catch problems before they become permanent.
How Do You Keep This Arrangement Dignified, Not Just Legal?
The rules tell you what's required. They don't tell you how to make this feel like partnership instead of surveillance, and that distinction matters most for people managing this alone or with a friend rather than a spouse.
Start with an honest conversation before anything is official. Talk through spending preferences, what "current needs" actually means to you, and where your comfort line is around sharing financial details. A prospective payee who understands your values before day one is far less likely to make decisions that feel like overreach later.
A few habits make the arrangement work smoothly:
- Keep a dedicated account for the beneficiary's funds and save every receipt, a practice SSA itself points to as a payee's best protection against misuse allegations
- Share monthly statements with the beneficiary, even informally, so nothing feels hidden
- Schedule a short recurring check-in, quarterly is often enough, to review spending together
- Involve the beneficiary in decisions whenever their capacity allows, rather than deciding unilaterally
Pro Tip: If you don't have a family member or close friend you'd trust with this level of responsibility, an organizational payee is a legitimate option. Some can charge limited, SSA-approved fees for the service, detailed in SSA's Guide for Organizational Representative Payees.
Solo agers often build their support network in pieces rather than relying on one person for everything, and that's exactly the approach Aging Solo's guide to maintaining independence at home walks through: layering trusted people, clear documentation, and honest conversations so no single relationship carries the whole weight of your care.
Key Takeaways
A representative payee arrangement works when the payee prioritizes the beneficiary's current needs, keeps meticulous records, and treats the role as a partnership rather than control.
| Point | Details |
|---|---|
| Definition matters | SSA, not a power of attorney or joint account, is the only entity that can legally appoint a representative payee. |
| Application requires presence | SSA weighs frequency of contact heavily, so the person who sees the beneficiary most often is usually the strongest candidate. |
| Recordkeeping is protection | Keeping receipts and a dedicated account for at least two years is a payee's best defense if SSA ever reviews the case. |
| Advance designation helps solo agers | Naming up to three preferred payees in advance lets SSA prioritize people you trust if the need ever arises. |
| Appeals have a clock | Beneficiaries can challenge a payee decision, but the appeal generally must be filed within 60 days. |
What the Rules Don't Tell You About Being Someone's Payee
Most explainers stop at compliance: keep receipts, meet deadlines, avoid disqualification. That's necessary, but it treats the relationship like a liability to manage rather than a role someone is trusting you with.
The conventional advice undersells frequency of contact. SSA doesn't just check a box on it, they use it as a proxy for whether you actually understand what this person needs month to month. If you're only reading bank statements and never talking to the beneficiary about their preferences, you're technically compliant and quietly failing the spirit of the role.
Here's what I'd prioritize first: the conversation before the application. Sit down and talk through what dignity looks like to the beneficiary specifically. Some people want to see every transaction. Others just want to know their rent is handled and be left alone otherwise. SSA's forms won't ask you that question, but it's the one that determines whether this arrangement feels like support or supervision. Get that right, and the recordkeeping becomes easy. Get it wrong, and even perfect paperwork won't fix the relationship.
— Mike
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Disqualifies You From Being a Payee?
Federal rules under CFR § 404.2022 generally disqualify people with certain felony convictions, prior findings of benefit misuse, creditors of the beneficiary, and people who themselves receive benefits through a payee. SSA can grant case-by-case exceptions when it serves the beneficiary's best interest.
Which Bank Is Best for a Representative Payee Account?
SSA doesn't endorse specific banks, but it requires the account be titled to clearly show it holds the beneficiary's funds, separate from the payee's personal money. Most payees choose whichever local bank or credit union makes that separate titling and easy recordkeeping straightforward.
How Long Does It Take to Become Someone's Payee for Social Security?
Timelines vary by local office workload and how quickly you can complete the SSA-11 form and attend the face-to-face interview. If the situation is urgent, such as a beneficiary at risk of losing housing, tell SSA directly, as offices can sometimes prioritize those interviews.
What Are the Rules for a Social Security Representative Payee?
Payees must use funds for the beneficiary's current needs first, conserve any leftover money appropriately, keep detailed records including receipts and bank statements, and report as SSA requests. Misuse can lead to repayment demands, removal as payee, and legal consequences under SSA's oversight guidelines.